

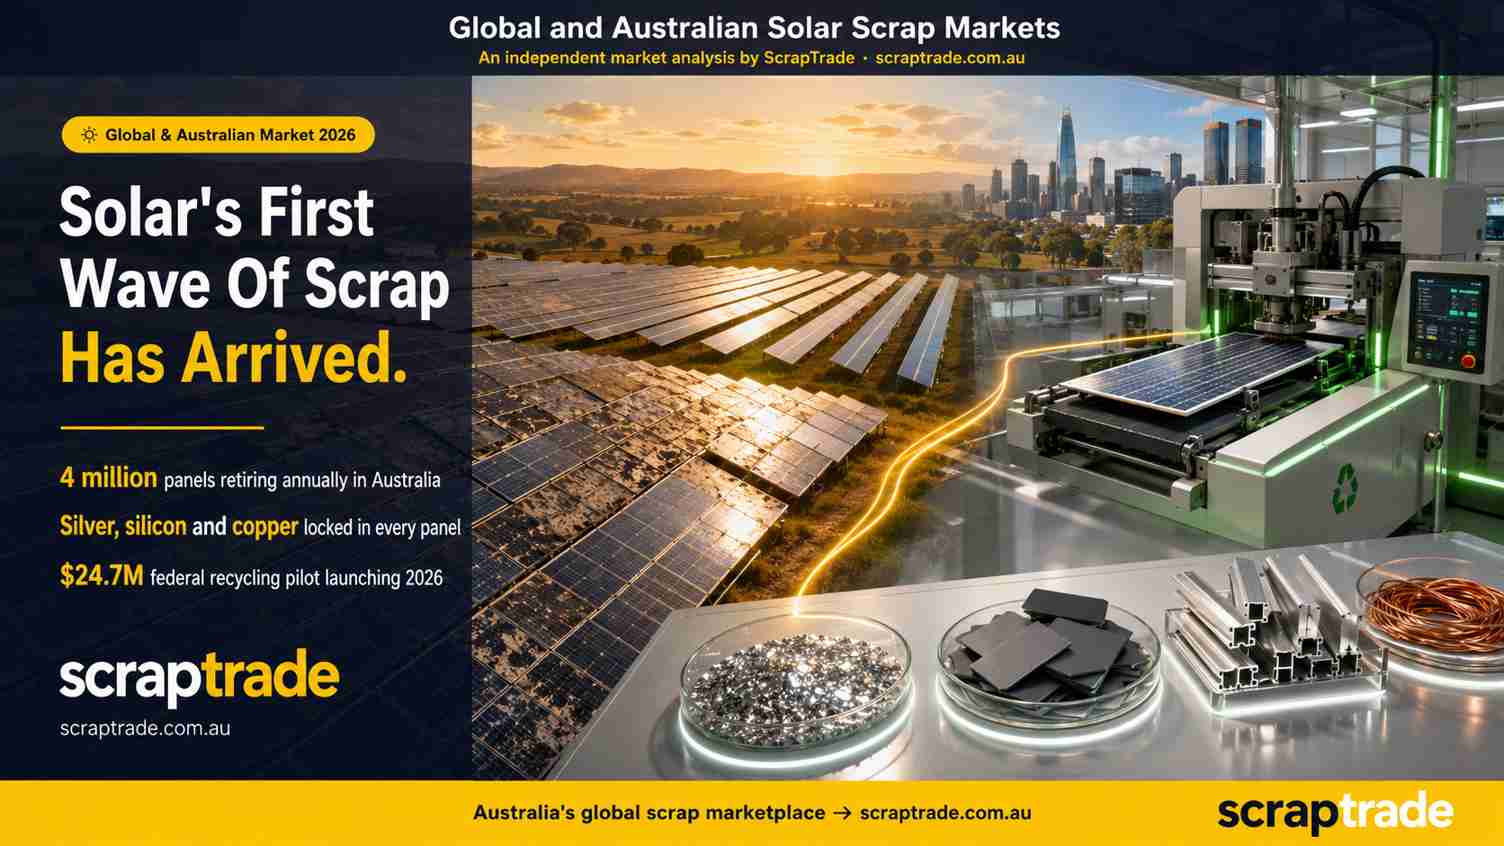
Global and Australian Solar Photovoltaic Scrap Markets: A Comprehensive Market, Policy, and Technological Evaluation
Global Market Projections and Regional Capacity Dynamics
The global transition toward renewable energy has driven a rapid increase in solar photovoltaic (PV) installations. By the end of 2022, global solar installations totaled over 178 gigawatts (GW), bringing the global cumulative capacity to approximately 1.2 terawatts (TW). By the end of 2023, cumulative renewable energy capacity reached 3,870 GW, with solar energy contributing a substantial 345.5 GW increase in that year alone. This growth is projected to continue, with global installed PV capacity expected to reach 5.46 TW by 2030 and 18.2 TW by 2050 to align with the International Renewable Energy Agency (IRENA) 1.5°C climate scenario.
This rapid buildout of solar infrastructure will inevitably lead to a corresponding wave of decommissioned solar panels as early systems reach the end of their operational lives. While standard panels are designed to last 25 to 30 years, early-loss scenarios—where panels are decommissioned prematurely due to weather damage, component degradation, or voluntary early replacement—are accelerating the growth of the solar scrap stream. The volume of global end-of-life (EoL) solar panels is projected to rise from 1.7 million tonnes in 2030 under regular-loss assumptions to as much as 8 million tonnes under early-loss projections. By 2050, cumulative global solar waste is projected to reach between 60 million and 78 million tonnes.
The financial scale of the solar panel recycling market has attracted significant attention from market research firms, though their exact growth projections vary depending on the forecasting models and assumptions used.
| Market Research Firm | Base Year Value (USD) | Projected Market Value (USD) | Forecast Period | Compound Annual Growth Rate (CAGR) |
|---|---|---|---|---|
| SkyQuest | USD 288.32 Million (2026 Projection) | USD 739.77 Million | 2026 – 2033 | 12.50% |
| Fortune Business Insights | USD 365.76 Million (2025) | USD 1,494.38 Million | 2026 – 2034 | 16.13% |
| Maximize Market Research | USD 257.96 Million (2025) | USD 610.65 Million | 2025 – 2032 | 13.10% |
Regional variations in the solar recycling market are shaped by early deployment patterns and the presence of local regulatory frameworks. In 2025, Europe dominated the global solar panel recycling market, holding an 87.39% market share, a position driven by the early adoption of solar technology across the European Union and the implementation of mandatory recycling legislation.
Meanwhile, the Asia-Pacific (APAC) region is projected to register the fastest compound annual growth rate over the coming decade, driven by rapid solar capacity expansion in China, India, and Japan, alongside growing public and private research and development funding. In the APAC region, China currently leads in patent filings related to solar panel recycling technology, reflecting a domestic focus on managing the waste streams from its massive solar manufacturing and installation bases.
| Country | Solar PV Installed Capacity and Waste Projections |
|---|---|
| China | Led global solar installations in 2022 with over 105 GW installed, bringing cumulative capacity to over 205 GW. Acts as the global leader in recycling patent filings to manage future waste streams. |
| United States | Installed approximately 21 GW of solar capacity in 2022, bringing cumulative capacity to 142 GW. Cumulative solar waste is projected to reach 9.1 million metric tons by 2050. |
| Japan | Cumulative installed capacity reached approximately 62 GW by 2023. The government is currently developing PV-specific recycling regulations to manage impending retirements. |
| Germany | Cumulative installed capacity reached 48.9 GW by 2023. Deployed solar panels contain an estimated 3.5 million tons of glass, 600,000 tons of aluminum, and 1,800 tons of silver. |
| India | Cumulative installed capacity reached 34.8 GW by 2023. Represents a high-growth market with a rapidly expanding solar scrap sector. |
The Geopolitical and Resource Security Dimensions of Solar Recycling
The growth of the solar recycling sector is increasingly tied to issues of supply chain resilience and geopolitical resource security. Traditional solar panel manufacturing relies on a concentrated global supply chain dominated by Chinese production, which accounted for 86% of global polysilicon production in 2022 and approximately 90% of solar glass production in 2023. For nations in the Global North, expanding domestic solar recycling capacity is seen as a strategic opportunity to diversify supply chains, reduce dependence on imported raw materials, and recover critical minerals.
According to the International Energy Agency's Roadmap to Net Zero Emissions by 2050, establishing systematic, commercial-scale solar recycling could reclaim enough secondary raw materials to meet 20% of the global solar industry's demand for aluminum, copper, glass, and silicon, and nearly 70% of its demand for silver. The recovery of these materials is also highly relevant given the global distribution of the waste trade, where approximately 45% of the total global value of trade in waste, scrap, and secondary goods currently occurs between high-income countries.
The material value of solar scrap is concentrated in a small fraction of the panel's overall mass. While low-value materials such as glass (70% to 75% of weight) and aluminum frames (10% to 15%) make up the vast majority of a standard crystalline silicon module's mass, trace metals like copper (1%) and silver (0.05%) represent the primary economic drivers for recovery. Silver, in particular, accounts for nearly half of the total material value in standard crystalline silicon panels.
This concentration of value makes the solar industry vulnerable to resource constraints. Extractive metallurgy experts warn that at current production rates, the global solar industry could exhaust known silver reserves within five years unless commercial-scale recycling infrastructure is developed to recover the metal from decommissioned panels. This resource bottleneck has shifted the focus of solar recycling toward "urban mining," treating end-of-life solar modules as complex, metal-rich secondary ores rather than simple waste products.
Technological Milestones in Material Extraction and Recovery
Developing recycling technologies that can recover high-purity materials is essential to make solar recycling economically viable and support a closed-loop industry. Traditional recycling methods rely on mechanical shredding, which crushes whole panels into low-value mixed fractions, making the separation of high-purity silicon and precious metals difficult. To address this issue, research centers and private cleantech firms are developing advanced chemical, thermal, and mechanical separation processes.
Pyrolysis and Chemical Upcycling: ROSI
The French industrial cleantech firm ROSI has developed a commercial-scale, chemical-based recycling process that recovers high-purity materials. Rather than shredding modules, ROSI uses controlled thermal processing (pyrolysis) to dissolve the ethylene vinyl acetate (EVA) polymer sheets that bind the solar cells to the protective glass and backsheet. This process isolates the active layer of the solar cell, allowing the company to recover 99.9% pure silicon and silver.
Because of their high purity, these recovered materials can be reused in high-value applications, such as semiconductor manufacturing, new solar panels, and fiber optics. Additionally, this recycling process saves approximately 90% of the energy and emissions required to produce virgin materials from raw quartz.
To fund its expansion, ROSI raised over EUR 20 million in a Series B round on April 28, 2026, led by InnoEnergy, CMA CGM, the European Innovation Council (EIC), and Spanish family office G3T. This funding will support enhancements to ROSI’s first industrial plant, ROSI Alpes in France, and fund the construction of a new 10,000-tonne-per-year facility in Teruel, Spain, under the INSPIRE-PV project.
To build out its processing and supply chains, ROSI has established strategic partnerships with Soren in France, SENS in Switzerland, the precious metals refiner Metalor (to process recovered silver), and AGC Glass Europe (to recycle recovered high-transparency glass). The company’s leadership team includes nanotechnology and industrial experts, such as President and Co-founder Dr. Yun Luo, World Industrial Director Daniel Bajolet, and Chief Technology Officer Guy Chichignoud.
Patented Mechanical Pre-Treatment and Sieving: UNSW ProMO Lab
In Australia, the Australian Research Council (ARC) Hub for Photovoltaic Solar Panel Recycling and Sustainability (PVRS) was launched at the University of New South Wales (UNSW) in April 2024. Backed by a AUD 5 million ARC grant and led by Professor Yansong Shen, the hub brings together a team of 30 researchers to develop recycling and material separation technologies.
A major milestone from this research is a patented mechanical pre-treatment process developed by the ProMO lab. To avoid the material contamination common in traditional shredding, the UNSW team introduced stainless steel balls as "sieving aids" inside a vibrating container.
This abrasive separation process selectively crushes the brittle silicon solar cells into fine particles while leaving the protective glass sheet intact at the top of the container. The entire process takes between 5 and 15 minutes and separates 99% of the solar cell material.
Once the silicon and silver particles are separated, the team uses targeted chemical leaching and selective precipitation to recover 99% of the silver from the cell matrix. Professor Shen has emphasized that to scale these laboratory breakthroughs into industrial operations, the sector must recruit more process and metallurgical engineers, advising that they should make up at least 30% of the technical workforce.
Advanced Material Processing and Quality Characterization: Fraunhofer CSP
The Fraunhofer Center for Silicon Photovoltaics (CSP) in Germany combines mechanical classification, wet chemical etching, and optical sorting to process crystalline silicon modules. Fraunhofer has demonstrated that silicon recovered from decommissioned modules can be purified, crystallized into new silicon ingots, sliced into wafers, and processed into functional PERC solar cells. To verify the purity of these secondary raw materials down to the parts-per-billion (ppb) range, Fraunhofer uses Glow Discharge Mass Spectrometry (GDMS), employing a Thermo Scientific Element GD spectrometer on polished solid silicon samples.
The institute uses a range of specialized equipment to optimize and evaluate its recycling processes:
- Comminution and Shredding: Single-shaft shredders, cutting mills, ball mills, and jaw crushers to mechanically break down module components.
- Mechanical and Optical Sorting: Tumbler screens, magnetic tape cutters, electrostatic corona drum separators, and air separation tables.
- Thermal Processing: Continuously operable rotary kilns, muffle furnaces, and specialized incinerators.
- Wet Chemical Etching: Etching baths with volumes up to 300 liters to clean wafer surfaces and dissolve target metals, paired with diffusion dialysis systems to recycle spent etching chemicals.
Encapsulation-Free Ecodesign: NREL
The National Renewable Energy Laboratory (NREL) in the United States is addressing recycling challenges by redesigning solar panels to be easier to disassemble. The Durable Module Materials Consortium, led by NREL, is conducting a proof-of-concept study on polymer-free solar modules.
Standard panels use plastic polymer sheets (EVA) to laminate the silicon cells, which requires high temperatures to loosen and makes recycling difficult. NREL's proposed design uses femtosecond infrared lasers to form glass-to-glass edge welds, creating a hermetic seal without the need for polymer adhesives.
Because the heat of the laser is confined to a few millimeters from the weld, it does not damage the temperature-sensitive silicon cells. At the end of the panel's life, the glass can be shattered, allowing the glass, silicon, and copper wiring to be separated and recycled without chemical or thermal processing.
| Recycling Technology Developer | Processing Mechanism | Key Materials Recovered & Purity Levels | Processing Capacity or Milestone |
|---|---|---|---|
| ROSI (France & Spain) | Pyrolysis-based chemical recycling to decompose polymer sheets. | Recovered silicon and silver at 99.9% purity. | Scaling up to 10,000 tonnes per year at the Teruel, Spain facility. |
| UNSW ProMO Lab (Australia) | Abrasive mechanical vibration using stainless steel balls as sieving aids. | Separation of 99% of PV cell particles; extraction of 99% of silver. | 5-to-15-minute processing cycle; supported by federal ARENA and NSW EPA grants. |
| Fraunhofer CSP (Germany) | Mechanical sorting combined with wet chemical etching up to 300 liters. | Solar-grade silicon, aluminum, copper, and silver. | Silicon purified to manufacture new PERC cells; verified with ppb-level GDMS. |
| NREL (United States) | Femtosecond laser welding to create direct glass-to-glass hermetic seals. | Glass, silicon, and metal wires easily separated after shattering. | Elimination of polymer laminates; module passed static load testing. |
Global Regulatory Models and Policy Implementations
The commercial viability of solar panel recycling is shaped by local regulatory models and government policies. The presence of landfill bans and Extended Producer Responsibility (EPR) mandates is often the deciding factor in whether a regional solar recycling industry can develop.
The European Union’s WEEE Directive
The European Union has the most established regulatory framework for solar recycling. In 2012, solar panels were included in the Waste Electrical and Electronic Equipment (WEEE) Directive, which applies Extended Producer Responsibility (EPR) to the solar sector. Under this directive, manufacturers and importers selling PV panels in the EU are legally responsible for financing the collection, transport, and recycling of those panels at the end of their lives.
This is funded through an "eco-fee" (typically EUR 0.05 to EUR 0.20 per kilogram) added to the purchase price of new panels, providing a stable source of revenue for recyclers. The directive also mandates a minimum 75% to 80% material recovery rate by weight, preventing recyclers from simply shredding modules for low-value waste.
In Italy, Legislative Decree 118/2020 updated the transposition of the WEEE Directive, requiring accredited collective compliance systems to take responsibility for collecting and treating decommissioned panels. Under the IV and V Conto Energia incentive programs, system operators must register panel serial numbers and provide financial guarantees to ensure long-term funding for recycling, which helps mitigate the risk of illegal dumping or improper disposal.
United States: State-Level Policy Variations
In the United States, there are no federal regulations mandating the recycling of solar panels. Under the federal Resource Conservation and Recovery Act (RCRA), solar panels must undergo Toxicity Characteristic Leaching Procedure (TCLP) testing to determine if they contain hazardous levels of lead or cadmium.
Because landfilling non-hazardous panels remains inexpensive (USD 1 to USD 5 per panel) compared to the cost of recycling (USD 15 to USD 45), less than 10% of decommissioned US panels are currently recycled. In response, several states have implemented their own regulations:
- California: Under Senate Bill 489, California became the first state to classify decommissioned solar panels as "universal waste" (effective January 1, 2021) to simplify the recycling process. This rule reduces the administrative burden on handlers, allowing them to accumulate panels for up to one year without a hazardous waste manifest. Handlers must still notify the Department of Toxic Substances Control (DTSC) and submit annual reports by February 1 if they process more than 100 kilograms of panels from offsite sources.
- Washington State: Passed Senate Bill 5939 in 2017, establishing a Photovoltaic Module Stewardship and Takeback Program that requires manufacturers to fund and operate convenient recycling programs for panels sold after July 1, 2017. However, during the 2025 legislative session, the state delayed the implementation of the law, pushing the deadline for manufacturer-approved stewardship plans from July 1, 2025, to January 31, 2031. This delay was requested by the Department of Ecology to prevent some manufacturers from withdrawing their products from the Washington market, which would have increased costs and reduced panel availability for low-income solar programs.
Commercial Scaling: SolarCycle
Despite the lack of federal mandates, commercial solar recycling in the United States is scaling through market-driven initiatives. SolarCycle, a technology-driven recycling platform established in 2022, has built a network of processing facilities in Texas, Georgia, Arizona, Nevada, and Illinois.
The company uses patented mechanical and thermal processes to extract up to 95% of a panel's material value, returning aluminum, glass, copper, silicon, and silver to domestic manufacturing supply chains. SolarCycle has processed over 500,000 panels—more than any other recycler in North America—and has secured exclusive recycling agreements with major solar operators, including Prologis (for its 1 GW rooftop portfolio) and RWE Clean Energy.
The company is also constructing a 1.1 million-square-foot factory to manufacture solar glass from recycled panels, creating a localized, closed-loop supply chain for US module assembly.
The Australian Solar Scrap Market and Commercial Landscape
Australia represents a critical market for solar scrap research due to its high per capita rooftop solar capacity. As of late 2024, approximately 4 million residential solar systems had been installed across the country, with an additional 300,000 rooftop systems added annually.
Decommissioning Waves and the Early-Replacement Trend
This massive installation base is driving a steep waste curve as early rooftop systems, commissioned between 2010 and 2016, approach their retirement window. National end-of-life PV waste is projected to rise from approximately 59,000 tonnes in 2025 to over 91,000 tonnes annually by 2030, eventually reaching a cumulative total of 1 million tonnes (equivalent to 50 million panels) by 2035.
| Year | Projected Annual Solar Waste (Tonnes) | Notes and Industry Milestones | Source |
|---|---|---|---|
| 2025 | 59,000 – 60,000 | Early residential replacement, warranty failures, storm damage | [cite: 6, 42] |
| 2026 | 30,000 – 40,000 | Primarily residential and early commercial systems | [cite: 43] |
| 2030 | ~90,000 – 100,000 | Mid-generation residential retirements; early commercial repowering | [cite: 43, 44, 45] |
| 2035 | 150,000 – 180,000 | Influx of utility-scale solar farm decommissionings (cumulative total exceeds 1,000,000 tonnes) | [cite: 42, 43] |
| 2050 | >1,500,000 | Projected cumulative national solar waste volume | [cite: 42] |
A key issue in Australia is the trend of early decommissioning. While theoretical waste models assume a panel lifespan of 25 to 30 years, empirical data from trials in Queensland reveal that a significant portion of decommissioned panels are only 7 to 10 years old.
This early replacement is driven by rapid drops in the cost of new panels and significant efficiency improvements, which encourage homeowners to upgrade their systems before they reach end-of-life. If this voluntary early replacement trend continues across all states, actual Australian solar waste volumes by 2035 could be significantly higher than current projections.
This trend is further complicated by a lack of financial incentives for panel reuse. Research commissioned by the federal government indicates that second-hand panels are rarely cost-effective, as the high installation, permitting, and compliance costs of used systems outweigh their lower purchase price, making new, high-efficiency systems a more attractive option for most consumers.
Exporting used panels is also subject to strict international regulations; under the Hazardous Waste (Regulation of Exports and Imports) Act 1989, panels classified as hazardous e-waste cannot be legally exported unless their reusability can be demonstrated in accordance with the Basel Convention Technical Guidelines.
State Regulatory Frameworks and Landfill Bans
In response to the growing volume of solar waste, Australian states are transitioning from voluntary guidelines to mandatory stewardship models, though this transition remains fragmented across different jurisdictions:
- Victoria (VIC): Decommissioned panels, inverters, and battery storage systems are classified as "specified e-waste" and strictly banned from landfills. Under the Environment Protection Regulations 2021, solar installers and retailers must ensure all decommissioned equipment is taken to EPA-authorized collection hubs or certified recyclers. Non-compliance is an indictable offense with substantial statutory penalties. In March 2025, Solar Victoria updated its Notice to Market to make these recycling requirements mandatory for all retailers participating in the Solar Homes Program, recommending that end-of-life management be certified to Australian Standard AS 5377.
- Western Australia (WA): Implemented the Waste Avoidance and Resource Recovery (e-waste) Regulations 2024 on July 1, 2024, prohibiting the disposal of solar panels and electrical waste in landfills. To support this ban, the Western Australian government allocated EUR 10 million in its 2026-27 budget under the Remade in WA initiative. This funding includes EUR 7.3 million for solar collection networks and recycling pathways, and EUR 1.7 million to establish battery collection points.
- Queensland (QLD): In August 2024, Queensland launched the Solar Panel Stewardship pilot program in partnership with the Smart Energy Council. Funded by AUD 5.5 million from the Recycling and Jobs Fund, the program established six confirmed collection sites (Capalaba, North Lakes, Gold Coast, Toowoomba, Rockhampton, and Townsville) to assess the feasibility of processing residential and utility-scale solar waste.
- New South Wales (NSW): The state assented to the Product Lifecycle Responsibility Act 2025 on April 9, 2025. While not yet in force, the Act places strict lifecycle responsibility on brand owners to manage their products from design to end-of-life disposal. NSW also implemented updated renewable energy guidelines in November 2024, which require utility-scale developers to submit formal decommissioning plans and introduce a standard "decommissioning calculator" to estimate end-of-life liability.
To unify these state-level efforts, the Australian Federal Government announced an AUD 24.7 million investment over three years starting in January 2026 to fund a national solar panel recycling pilot. This pilot program aims to establish up to 100 collection sites nationwide and process up to 250,000 decommissioned panels. The data collected from the pilot will be used to design a mandatory national product stewardship scheme, as recommended by the Productivity Commission's January 2026 report on Australia's circular economy.
The Commercial Landscape and $7 Billion SMB Opportunity
The impending decommissioning wave represents a significant commercial opportunity for Australian small and medium-sized businesses (SMBs). While residential panels dominate early waste streams, a larger volume of waste is expected starting in 2028 as early utility-scale solar farms (200 MW to 500 MW facilities built between 2008 and 2012) begin decommissioning.
The Clean Energy Council and industry analysts estimate that establishing a comprehensive collection, logistics, and processing sector to handle these retired assets could unlock up to AUD 7.3 billion in economic benefits through reduced waste and the reuse of recovered materials.
To participate in this emerging market, operators must establish compliant logistics and data-tracking systems. Every panel moving through a certified facility must generate waste tracking records, chain-of-custody documentation, recycling certificates, and EPA compliance reports to satisfy emerging Extended Producer Responsibility (EPR) reporting requirements starting in 2028-2029.
| Company / Initiative | Processing Location(s) | Primary Recycling & Upcycling Technologies | Key Material Outputs and Operational Scale |
|---|---|---|---|
| Elecsome | Keysborough & Kilmany, VIC; Richmond Valley, NSW; Toowoomba, QLD; East Pilbara, WA. | Mechanical de-framing and upcycling of recovered glass into specialized aggregates. | Deploys "Solarcrete," a nano-engineered pre-mix concrete replacing aggregate with solar glass fines; partner of AGL. |
| Lotus Recycling | Campbellfield (Thomastown), VIC. | Automated mechanical sorting and separation without chemicals. | Recycles panels, inverters, cabling, and mounting structures; provides Official Recycling Certificates; excludes toxic cadmium telluride. |
| Reclaim PV | Lonsdale, SA; Brisbane, QLD. | Pyrolysis thermal extraction to decompose EVA polymer encapsulants. | 100% material reclamation including glass, silicon, and precious metals; recycling partner of Tindo Solar. |
| PV Industries | New South Wales. | Physical de-framing and glass separation using specialized mechanical systems. | Processes frames, cabling, junction boxes, and glass; funded by NSW EPA Circular Solar Phase 2 grant. |
| Cyber Recycling | Canning Vale, near Perth, WA. | Mechanical and physical separation of crystalline silicon panels. | Initial capacity of 2,500 panels per year, scaling to 22,500 tonnes per year to support WA's landfill ban. |
| Ecoactiv | Melbourne, VIC (with nationwide pickup). | Direct collection logistics and automated sorting. | Nationwide collection and transport network with online booking and tracking. |
| Circular PV Alliance | National. | Technical refurbishment, testing, and safety validation. | Refurbishes functional decommissioned panels for second-life energy access in developing communities. |
| Solarec | National. | Dedicated Photovoltaic Materials Recovery Facility (MRF). | Processes bulk solar scrap to recover glass, aluminum, and copper. |
Strategic Analysis and Future Industry Outlook
The global and Australian solar panel recycling markets are transitioning from a fragmented, policy-dependent sector to a structured, resource-recovery industry. This transition is driven by three main factors: growing waste volumes as early installations reach end-of-life, tightening environmental regulations and landfill bans, and the rising value of recovered raw materials.
Overcoming the Structural and Economic Bottlenecks
The primary challenge facing the industry is the persistent cost gap between inexpensive landfilling and expensive recycling. To close this gap and achieve commercial viability without relying on ongoing public subsidies, the industry must implement three key reforms:
- Ecodesign Integration: Solar manufacturers must design modules that are easier to recycle, moving away from tough polymer adhesives (EVA) and toward clean-separating alternatives, such as NREL's laser-welded glass-glass edge seals.
- High-Purity Material Recovery: Recyclers must transition from basic mechanical shredding (which yields low-value mixed waste) to high-efficiency separation processes, such as the pyrolysis-based chemical recycling developed by ROSI and the mechanical-sieving process developed by UNSW. Recovering solar-grade silicon and precious metals at high purity significantly improves the economic returns of recycling.
- Policy and Regulatory Harmonization: Governments must replace fragmented, state-level regulations with national, mandatory Extended Producer Responsibility (EPR) schemes, as seen in the European Union’s WEEE Directive. In Australia, establishing a national product stewardship scheme, supported by consistent state-level landfill bans and strict export controls, is essential to secure a stable supply of recycling feedstock and attract private investment.
Achieving Long-Term Circularity
By aligning policy, technology, and manufacturing design, the solar industry can transform its looming end-of-life waste challenge into a sustainable, secure source of critical minerals. Establishing a robust, closed-loop recycling infrastructure will not only reduce the environmental footprint of solar technology but also help secure domestic supply chains for the next generation of solar panels, supporting the long-term sustainability of the global energy transition.