

Market Structural Transition, Material Access, and Resource Protectionism: An Analytical Report on the United States Scrap Metal Industry (2025–2026)
Macroeconomic and Economic Contributions of the Scrap Sector
The United States scrap metal recycling industry represents a critical foundation of the nation's industrial supply chain, acting as a crucial raw material provider for advanced manufacturing, construction, and infrastructure development. The global scrap metal recycling market was valued at approximately $435.50 billion to $436.11 billion in 2025. Driven by aggressive decarbonization mandates, the transition to low-emission manufacturing, and rising commodity valuations, this global market is projected to grow from $451.00 billion to $458.70 billion in 2026, progressing at a compound annual growth rate (CAGR) of 5.18% to reach approximately $614.00 billion by 2034 and $722.65 billion by 2035.
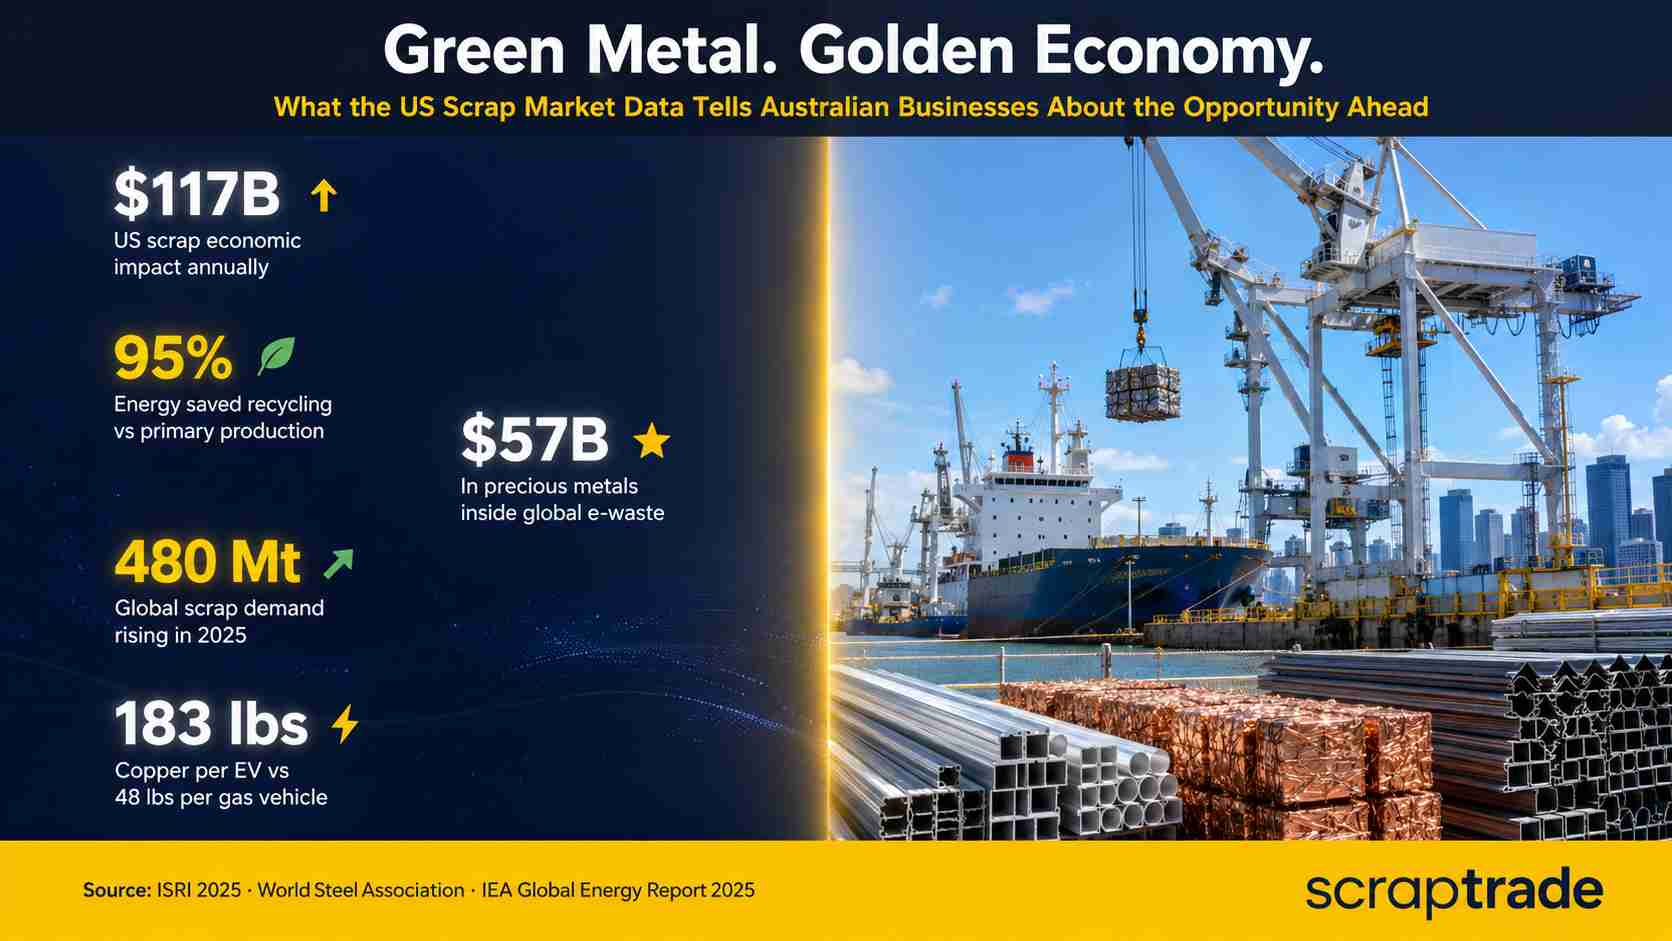
The domestic economic footprint of this sector is substantial. Within the United States, the recycling industry generates a total economic impact of $117 billion, directly employing over 160,000 workers and contributing approximately $13 billion in federal, state, and local tax revenues. This vast network consists of more than 7,000 scrap recycling facilities nationwide, including approximately 300 highly automated shredder plants.
The market features a mixture of high consolidation and local decentralization. While the top five scrap recycling corporations control about 15% of the total domestic market share, small businesses account for approximately 75% of industry participants. The longevity of these operations highlights their resilience, with 50% of United States scrap processors having operated continuously for over 25 years.
| Market Metric (2025–2026) | Regional or Segment Share | Primary Industrial Driver |
|---|---|---|
| Asia-Pacific Global Share (2025) | 48% | Steelmaking capacity expansion, regional urbanization |
| Ferrous Segment Share (2025) | 75% | Structural steel demand, automotive manufacturing |
| Old Scrap Source Share (2025) | 60% | End-of-life vehicle recycling, structural demolition |
| Building & Construction End-Use Share | 38% | Public infrastructure projects, commercial real estate |
| Automotive Growth Forecast (CAGR) | 4.7% | EV lightweighting, vehicle end-of-life recycling acceleration |
| United States Industry Economic Impact | $117 Billion | Manufacturing and EAF steelmaking operations |
Geographically, the Asia-Pacific region dominated the global recycling market with a 48% share in 2025. However, North America is forecasted to expand at the fastest CAGR between 2026 and 2035. This acceleration is driven by the rapid adoption of electric arc furnaces (EAFs)—which process over 90% of United States scrap steel—and massive investments in localized manufacturing loops. The non-ferrous segment is expected to grow at the fastest CAGR of 4.6% during this forecast period, reflecting the rising demand for lightweight, corrosion-resistant metals such as copper, aluminum, and zinc in electric vehicle (EV) production and advanced electronic applications.
The Regulatory Framework and Circular Economy Dynamics
The regulatory environment in the United States increasingly acts as both a compliance burden and a structural driver for scrap recovery. Domestically, recycling facilities operate under stringent environmental protections. Under the Clean Water Act, scrap yards must maintain active stormwater runoff permits, and the Clean Air Act mandates 100% refrigerant recovery from all discarded scrap air conditioning units and appliances.
To align with corporate procurement mandates, 35% of large-scale scrap companies have secured formal ISO 14001 environmental management certifications. Concurrently, to combat metal theft, anti-theft laws across 45 states require scrap yards to hold payments for a mandatory three days before releasing funds to sellers, particularly for high-theft items like catalytic converters.
| Metal Type | Primary Energy Savings | Carbon and Ore Displacement Metrics |
|---|---|---|
| Aluminum | 95% | Saves 14,000 kWh per ton; secondary production cuts air pollution by 95% |
| Steel | 58% | Saves 1,100 kg of iron ore, 630 kg of coal, and 40% of process water per ton |
| Nickel | 75% | Lowers refining emissions; critical for EV battery chemistry |
| Magnesium | 90% | Accelerates automotive lightweighting loops |
| Copper | 85% | Avoids mining 200 tons of raw ore per ton of recycled metal |
The physical mechanisms of the circular economy provide massive environmental offsets. Globally, steel recycling prevents more than 900 million tons of carbon dioxide ($CO_2$) emissions annually, and using recycled steel scrap instead of primary ore reduces overall smelting emissions by 58%.
Electronic waste (e-waste) represents a high-value recycling frontier; reclaiming gold from electronic scrap generates 80% less carbon emissions than primary gold mining. Modern specialized e-waste facilities—which constitute approximately 5% of all active recycling centers—can recover up to 90% of the gold embedded in obsolete circuit boards, capturing value from a global e-waste stream that contains an estimated $57 billion in precious metals annually.
Ferrous Scrap Market: Historical Benchmarks, Domestic Supply, and Price Indices
The United States domestic ferrous scrap market is characterized by a strong structural demand base, driven by the steel industry’s transition toward low-carbon metallurgy. In 2024, domestic consumers processed 63 million tons of ferrous scrap, representing a 1.6% increase compared to 2023, while total export volumes of ferrous scrap were approximately 15 million tons, a decline of 6.25% year-on-year.
The primary sources of this material were post-consumer scrap (58%), new prompt industrial scrap generated in manufacturing plants (24%), and home scrap generated internally within steel mills (18%). By 2025, apparent domestic consumption of iron and steel scrap reached 57 million tons. This consumption was supported by elevated domestic raw steel production, which rose to 82 million tons in 2025 from 79.5 million tons in 2024, allowing steel mills to maintain capacity utilization rates of 75% to 80%.
The pricing of No. 1 heavy melting steel scrap delivered to domestic mills experienced minor positive adjustments, with the annual average composite price rising to $319.00 per metric ton in 2025, compared to $314.85 per metric ton in 2024. This baseline remains lower than historical highs, but reflects a stabilization of the raw material market.
| Year | No. 1 Heavy Melting Steel Composite Price | Total Value of Purchases | Apparent Consumption | Mill Operating Rate |
|---|---|---|---|---|
| 2021 | $417.66 per metric ton | $22.1 Billion | 58 Million Tons | 78% – 82% |
| 2022 | $381.72 per metric ton | $21.5 Billion | 57 Million Tons | 75% – 79% |
| 2023 | $333.28 per metric ton | $20.8 Billion | 55 Million Tons | 74% – 77% |
| 2024 | $314.85 per metric ton | $20.4 Billion | 55 Million Tons | 72% – 78% |
| 2025e | $319.00 per metric ton | $19.7 Billion | 57 Million Tons | 75% – 80% |
This long-term pricing stabilization is reflected in the Producer Price Index (PPI) for Material Recyclers: Ferrous Metal Scrap, maintained by the Federal Reserve. By April 2026, the PPI index registered at 522.275 (Dec 1986=100). While this index represents a recovery from historical baseline levels, it remains well below the record high of 754.730 achieved in March 2022, though significantly elevated above the historical record low of 98.600 in April 1987.
The short-term monthly index dynamics of 2025 and 2026 show significant seasonal volatility. According to industry indices, AMM #1 Steel Scrap prices started 2025 at $380.00 per ton, peaked in April at $480.00 per ton, and subsequently declined to a low of $390.00 per ton in November and December of 2025 as domestic mill utilization rates fluctuated.
The market entered 2026 on a stronger footing, with steel scrap prices rising to $400.00 per ton in January and peaking at $450.00 per ton in March, maintaining this elevated plateau through June 2026.
This early 2026 price surge was primarily supply-driven. Severe winter storms, freezing coastal weather, and localized logistics disruptions on the United States East Coast restricted physical scrap collection and processing. Consequently, domestic steel mills were forced to aggressively bid up purchase prices, particularly for shredded and prompt industrial grades, to prevent stockouts and maintain operating utilization rates.
However, this tight domestic supply environment conflicted with a weakening export front. On the East Coast, export prices for HMS 1/2 Scrap (80:20) fell by 2.2% in February 2026 to $333.00 per ton FOB. Turkish steelmakers, facing compressed margins on finished long products and high domestic inventories, resisted the elevated pricing of United States exporters.
This diverging market dynamic culminated in April 2026 when the Fastmarkets US Ferrous Scrap Trend Indicator dropped to 46.9, signaling a mild downside bias in pricing. The associated market consensus index plunged to a record low of 47.0, highlighting unprecedented uncertainty among buyers, brokers, and sellers. Buy-side sentiment was exceptionally weak at 40.7, as consumers expected a sharp downward correction in response to finished steel demand stagnation, whereas sellers and brokers remained neutral at 50.0.
This bearish sentiment proved temporary. By June 2026, the Trend Indicator recovered to 54.9, projecting a modest 2.0% month-on-month increase in pricing. Physical scrap inventory levels remained highly balanced at 50.7, indicating that steel mills were neither overstocked nor critically short of metallic units, leading to price stabilization at the $450.00 per ton mark.
| Steel/Iron Grade | 2026 Price Range | Processing Cost | Profit Margin | Primary Application & Drivers |
|---|---|---|---|---|
| Mild Steel | $200 – $250 / ton | $50 – $80 / ton | 15% – 25% | General structural steel, sheet metal |
| High-Strength Steel | $250 – $300 / ton | $80 – $120 / ton | 20% – 30% | Heavy equipment, structural columns |
| Scrap Cast Iron | $150 – $200 / ton | $40 – $60 / ton | 10% – 20% | Engine blocks, municipal piping |
| Shredded Steel | $200 – $250 / ton | $60 – $100 / ton | 15% – 25% | EAF automotive sheet feedstocks |
Non-Ferrous Metals: Electrification and Supply-Demand Deficits
While the ferrous segment dominates recycling by sheer physical volume, the non-ferrous metals segment represents the fastest-growing sector of the modern industry. This rapid expansion is fundamentally linked to the global energy transition, the scaling of regional electrical grids, and the manufacturing of high-purity electrical conductors.
The Copper Export Paradox and Resource Protectionism
Copper is the critical focus of global electrification, with demand driven by EV battery manufacturing, solar and wind power installations, and AI-enabled data center expansions. A standard internal combustion engine passenger car requires approximately 48 pounds of copper, whereas an electric vehicle requires 183 pounds, representing a 281% increase in unit metal intensity.
This massive structural demand is clashing with severe primary extraction constraints. Mining operations are struggling to expand capacity, with new global supply growing at only 1% to 2% annually, while annual demand is expanding at 3% to 4%, leading to a widening structural deficit.
This supply-demand imbalance has exposed a significant structural paradox in the United States scrap copper market. In 2024, the United States produced approximately 870,000 tons of recycled copper but exported 957,000 tons, sending over 40% of its high-quality secondary copper assets abroad, primarily to processing hubs in Asia.
To protect domestic manufacturing supplies and ensure resource security, major federal policy changes are scheduled to take effect in 2027. These upcoming protectionist regulations will mandate that a minimum of 25% of all high-quality copper scrap generated in the United States must remain within the domestic market. This regulatory shift is already forcing processors to secure domestic agreements and is expected to structurally inflate international copper scrap prices while constraining secondary smelting capacity in Europe and Asia.
| Metal Type | Annual Demand Growth | New Mine Supply Growth | Supply-Demand Balance Status |
|---|---|---|---|
| Copper | 3% – 4% | 1% – 2% | Widening Structural Deficit |
| Lithium | 20% – 25% | 15% – 18% | Tight Balance / High Volatility |
| Nickel | 5% – 7% | 4% – 6% | Slight Deficit |
| Aluminum | 2% – 3% | 2% – 3% | Balanced |
In the physical spot market, United States scrap copper prices began 2026 on a stronger footing than in 2025. In Q1 2026, scrap copper prices averaged between $3.80 and $4.50 per pound, representing a 5% to 15% year-over-year gain compared to the 2025 average range of $3.60 to $4.20 per pound. This price appreciation follows a historical baseline established in August 2025, when copper prices traded in a narrower range of $3.50 to $3.70 per pound.
Goldman Sachs Research projects that while a temporary global refined copper surplus of approximately 160,000 tons will keep London Metal Exchange (LME) spot prices bounded between $10,000 and $11,000 per metric ton in 2026 (averaging $10,710 in the first half of the year), structural mine supply deficits and aggressive AI data center upgrades will drive substantial long-term price appreciation.
| Copper Grade | 2025 Baseline Value | Expected 2026 Value | Primary Industrial Demand Driver |
|---|---|---|---|
| Bare Bright Wire | 95% – 98% of spot | 96% – 99% of spot | EV motor manufacturing, AI data centers |
| #2 Copper | 85% – 90% of spot | 87% – 92% of spot | Commercial construction, municipal utility grids |
| Copper Tubing | 90% – 94% of spot | 92% – 96% of spot | HVAC systems, industrial plumbing replacements |
| Insulated Wire | 45% – 65% of spot | 50% – 70% of spot | Demolition projects, electrical contracting scrap |
Aluminum and the Primary Smelting Deficit
The United States aluminum scrap sector is operating under an acute primary smelting deficit. Currently, only six primary aluminum foundries remain active in the United States, a decline that has made the domestic manufacturing sector almost entirely dependent on secondary scrap recycling. Aluminum recycling is highly energy-efficient, requiring 95% less energy than producing primary metal from bauxite ore, with every metric ton of recycled aluminum saving approximately 14,000 $kWh$ of electricity and reducing associated air pollution by 95%.
This supply-side structural change has turned aluminum scrap into a premium commodity. In 2024, the United States exported 2.4 million tons of aluminum scrap, a 17% increase over 2023, with export values in the first half of 2025 alone reaching $6.88 billion.
In Q1 2026, domestic aluminum scrap prices stabilized at $0.75 to $1.05 per pound, representing a 5% to 12% increase compared to the $0.70 to $0.95 per pound range of 2025. This price appreciation follows a historical baseline established in August 2025, when aluminum prices traded at $0.55 to $0.80 per pound.
This price appreciation is heavily supported by regional Midwest smelting premiums and the ongoing lightweighting trends in the automotive and aerospace manufacturing sectors.
Brass and Specialty Non-Ferrous Alloys
Brass scrap pricing remains closely correlated with the copper market due to its high copper content. In Q1 2026, scrap brass prices rose to an average range of $2.40 to $3.00 per pound, up from $2.20 to $2.80 per pound in 2025, marking a moderate gain of 5% to 10%. This price appreciation follows a historical baseline established in August 2025, when brass prices traded at $2.20 to $2.95 per pound.
Concurrently, other non-ferrous and specialty alloys—such as stainless steel—remained stable, with stainless steel scrap trading in an average range of $0.30 to $0.52 per pound, retaining its value due to its durability, versatility, and high alloying content.
| Non-Ferrous Grade | 2026 Price Range | Processing Cost | Profit Margin | Primary Application & Drivers |
|---|---|---|---|---|
| Clean Aluminum | $1,400 – $1,500 / ton | $100 – $150 / ton | 25% – 35% | Aerospace, secondary foundry ingots |
| Mixed Aluminum | $1,500 – $1,600 / ton | $150 – $200 / ton | 20% – 30% | Automotive sheet metal, casting scrap |
| Aluminum Radiators | $1,550 – $1,600 / ton | $130 – $180 / ton | 25% – 40% | HVAC recycling, engine cooling loops |
| Aluminum Extrusions | $1,600 – $1,700 / ton | $120 – $170 / ton | 30% – 45% | Architectural frames, window extrusions |
| Clean Copper | $5,500 – $5,800 / ton | $200 – $250 / ton | 30% – 40% | Electrical busbars, high-purity castings |
| Mixed Copper Scrap | $5,800 – $6,000 / ton | $250 – $300 / ton | 25% – 35% | General industrial scrap, cabling |
| Copper Tubing | $5,500 – $5,700 / ton | $180 – $230 / ton | 28% – 38% | Plumbing, heating, refrigeration |
| Copper Wire | $5,600 – $5,800 / ton | $200 – $250 / ton | 30% – 40% | Demolition, electrical contracting |
Strategic Landscape of Specialty Metals, Lead, Zinc, and Precious Metals
The non-ferrous and specialty metal scrap segments exhibit distinct operational dynamics, price ranges, and margins depending on processing complexity and supply chain integration.
Lead and Zinc Stabilization
Lead recycling represents one of the most successful closed-loop circular economies in the United States, boasting a battery recovery rate exceeding 99%. In 2026, lead scrap prices are projected to remain highly stable, fluctuating between $2,000 and $2,300 per ton, with processing costs averaging $150 to $200 per ton, yielding solid operating profit margins of 20% to 30%. Discarded lead-acid batteries command slightly lower prices of $1,500 to $1,800 per ton due to the hazardous nature of handling and neutralizing sulfuric acid during the smelting process.
Zinc scrap is showing positive demand momentum, driven by automotive and construction galvanizing requirements. Clean zinc scrap prices are forecasted to range from $2,500 to $3,000 per ton in 2026, with processing costs of $180 to $250 per ton and a profit margin profile of 25% to 35%. Zinc die castings maintain a premium pricing range of $2,800 to $3,000 per ton due to their high metallurgical purity and ease of direct remelting.
Precious Metals Recovery and E-Waste Valuations
Precious metal scrap remains highly volatile and sensitive to global macroeconomic sentiment, inflation hedging, and central bank purchasing policies. However, the industrial extraction of these metals from electronic waste (e-waste) is expanding rapidly. Globally, e-waste holds an estimated $57 billion in embedded precious metals annually.
Extracting these metals is highly carbon-efficient; reclaiming gold from electronic circuit boards generates 80% less carbon emissions compared to primary gold mining. Advanced specialized recyclers are capable of recovering up to 90% of the gold embedded in obsolete circuit boards, while pyrometallurgical processing loops are successfully recovering up to 95% of silver from complex electronic scrap.
| Specialty/Precious Grade | 2026 Price Range | Processing Cost | Operating Margin | Primary Industrial Driver |
|---|---|---|---|---|
| Lead Scrap | $2,000 – $2,300 / ton | $150 – $200 / ton | 20% – 30% | Grid storage, backup batteries |
| Lead Acid Batteries | $1,500 – $1,800 / ton | $100 – $150 / ton | 18% – 28% | Automotive battery recycling loops |
| Zinc Scrap | $2,500 – $3,000 / ton | $180 – $250 / ton | 25% – 35% | Galvanizing, rust prevention coatings |
| Zinc Die Castings | $2,800 – $3,000 / ton | $230 – $300 / ton | 25% – 35% | Automotive trim, structural castings |
| Gold Scrap | $30,000 / kg | $1,000 – $1,500 / kg | 40% – 50% | Electronics, jewelry, investment bullion |
| Silver Scrap | $1,000 / kg | $200 – $300 / kg | 35% – 45% | Solar panels, electronic solder, contacts |
| Platinum Scrap | $1,800 / kg | $400 – $600 / kg | 25% – 35% | Catalytic converters, lab equipment |
| Palladium Scrap | $2,400 / kg | $500 – $700 / kg | 20% – 30% | Automotive catalysts, electronics |
The processing of precious metal scrap requires substantial capital investment in refining chemistry and security. Gold scrap processing costs range from $1,000 to $1,500 per kilogram, yet it yields the highest profit margins in the industry, ranging from 40% to 50%. Conversely, palladium scrap, while valuable at $2,400 per kilogram, features higher relative processing costs ($500 to $700 per kg) and compressed margins of 20% to 30%, reflecting the metallurgical complexity of separating platinum-group metals from industrial catalysts and electronic components.
Global Trade Flows and Bilateral Scrap Movements
The international trade of scrap iron and steel is a critical component of global commodity supply chains. The United States exported a total of $5.45 billion in scrap iron in 2025, representing 14.2% of total global exports. The primary export destinations by value were Turkey ($1.27 billion), Thailand ($796 million), India ($741 million), Bangladesh ($432 million), and Mexico ($382 million).
The fastest-growing export markets between 2024 and 2025 were Thailand (+$383 million), Vietnam (+$105 million), and Greece (+$69.5 million). Imports of scrap iron into the United States totaled $2.07 billion in 2025, with Canada serving as the dominant supplier at $1.31 billion, followed by Mexico at $546 million.
| Trade Direction (2025) | Partner Country | Trade Value ($) | Year-on-Year Growth Metrics (2024–2025) |
|---|---|---|---|
| Exports | Turkey | $1.27 Billion | Continued primary export market |
| Exports | Thailand | $796 Million | Fastest-growing market (+$383 Million) |
| Exports | India | $741 Million | Decline of $355 Million (-31.7%) |
| Exports | Bangladesh | $432 Million | Sustained secondary melting feedstock |
| Exports | Mexico | $382 Million | Driven by regional manufacturing alignment |
| Imports | Canada | $1.31 Billion | Upward import growth (+$15 Million) |
| Imports | Mexico | $546 Million | Strongest regional import growth (+$92.9 Million) |
Short-term bilateral movements in early 2026 show rapid monthly expansion. In March 2026, the United States exported $670 million and imported $222 million of scrap iron, resulting in a positive trade balance of $448 million.
Between February and March 2026, monthly scrap iron exports increased by 56.8%, rising from $427 million to $670 million, driven by post-winter export clearing and a massive 310% year-on-year increase in shipments to Mexico ($99.5 million) and an 83.5% increase to Thailand ($119 million). Concurrently, monthly imports increased by 24.8% to $222 million, primarily sourced from Canada ($155 million) and Mexico ($36.3 million).
Technology-Driven Recovery and Metallurgical Purity
To insulate operating margins against fluctuating commodity prices, United States scrap processors are heavily investing in advanced sorting and operational technologies. In the modern recycling environment, physical contamination acts as a major value destroyer; the presence of trace elements like phosphorus, tin, and varnishes drastically devalues copper, aluminum, and steel scrap. To mitigate this, processors are shifting away from manual sorting toward automated sensor-based sorting plants.
A key technological advancement is the integration of Spectrometry, specifically handheld and inline X-ray Fluorescence (XRF) and Laser-Induced Breakdown Spectroscopy (LIBS). LIBS technology has improved the sorting accuracy of scrap aluminum alloys by 98%, enabling the precise separation of wrought and cast alloys in real time, which increases the final purity of the sorted aluminum scrap to 99%. Similarly, handheld XRF analyzers are now capable of identifying complex multi-element metal alloys in less than five seconds, allowing yard operators to instantly grade incoming loads and prevent the cross-contamination of high-value nickel and cobalt alloys.
Furthermore, facilities are deploying machine learning algorithms coupled with high-speed automated robotic sorting arms. These robotic arms can sort up to 60 distinct scrap items per minute, utilizing computer vision to detect and isolate unwanted non-metallic materials or low-grade alloys on conveyor belts moving up to 100 tons of material per hour.
On a larger structural scale, modern automobile shredder plants can completely reduce an entire passenger vehicle into small fragments in under 30 seconds. Advanced magnetic separation systems subsequently remove 99% of the ferrous fractions from the shredded mix, while high-frequency eddy current separators isolate non-ferrous particles as small as 1mm, ensuring maximum material recovery and driving up the overall efficiency of the secondary smelting loop.
Strategic Industry Conclusions
The strategic environment of the United States scrap metal industry in 2026 is defined by a critical transition from export-oriented volume models to localized, technology-driven material access models. Based on the structural pricing trends, policy mandates, and technological developments evaluated in this report, the following strategic actions are recommended for industry participants:
- Smelter and Refining Alignment: Scrap processors should prioritize long-term domestic supply contracts over spot export markets. With the impending 2027 copper protectionist mandate requiring 25% of high-grade copper scrap to remain within the United States, processors who establish immediate supply relationships with domestic secondary copper foundries and EAF steel mills will secure a major competitive advantage, insulating themselves from potential export-clearing bottlenecks and high ocean freight volatility.
- Targeted Capital Investment in Sorting Technologies: To capture the substantial price premiums of high-purity non-ferrous alloys, operators must invest in inline LIBS and XRF spectrometry sorting equipment. Upgrading sorting facilities to achieve 99% pure aluminum and copper fractions will allow processors to bypass low-grade scrap discounts, reduce processing costs, and maximize their profit margins, which currently reach up to 45% for premium extrusions.
- Integrated E-Waste and Battery Recovery Loops: Given the high profit margins (up to 50%) of precious metal scrap recovery and the massive $57 billion embedded value in annual e-waste, traditional scrap yards should diversify their collection streams to include end-of-life electronics and battery packs. Developing partnerships with specialized pyrometallurgical processors and automotive dismantlers will position operators to capture the high-value metallic components generated by the rapid scaling of the domestic EV and data center sectors.
- Proactive Risk Hedaging Against Sentiment-Pricing Decoupling: As demonstrated by the record-low consensus and extreme buy-side sentiment divergence in April 2026, physical scrap prices can decouple from downstream macroeconomic sentiments due to climate and logistics disruptions. Risk managers should implement flexible pricing mechanisms and inventory hedging programs to protect operating cash flows during periods where physical supply-side tight floors clash with bearish downstream manufacturing demands.